Showing posts with label CRUDE. Show all posts

Wednesday, October 28, 2026

The latest petroleum inventories (Oct-28-2026), AND more of my grumbling!

Off to the races...

Gasoline inventories rose, with all else falling. 


The consumption of gasoline continues to decline.


The pump price for gasoline continues to be in a moderating range, with diesel doing similarly. I would still expect upward pressure on diesel.


[WARNING] My opinion about a couple of things.

Some of the social media I follow has a guy proclaiming that lack of new refineries is the reason for the diesel price being so high.

A dose of reality... we export nearly 1.7M barrels a day of distillate. We could reduce distillate export, but considering the crude cocktail required in current optimal refinery opertion... the distillate price would fall, however the gasoline price would rise rather dramatically.

Of course another major refinery being built could still utilize the current crude cocktail, we would require more imports, although it would reduce the price of diesel and gasoline unlikely. An added refinery would also accompany the infrastrucure  investment in export facilities, as gasoline and diesel are traded internationally. 

The ability to refine more would make those cheaper prices more attractive in a global market. 

Besides, those billions of dollars set aside to build a major refinery, plus infrastructure to export more product would likely not achieve a net profit, as the expectation of all, is to eliminate crude from the equation over the next 30-40 years.

That's just my opinion. Any comments?


Wednesday, October 21, 2026

The latest petroleum inventories (Oct-21-2026), AND likely an unpopular opinion!

Another week and another report. Here goes...

Inventories edged up for crude and distillate fuel. However, gasoline dropped, as the total of all products decreased nearly 8.7M barrels. The SPR showed a 300K barrel withdrawal.


The consumption of gasoline fell ever so slightly, according to the latest data.

The pump price for gasoline continues to be in a moderating range, with diesel doing similarly. I would still expect upward pressure on diesel.

I should mention that distillate exports have fallen the past couple of weeks, but that might a couple of large ships not loading up. We should be nearing the end of US and Canada harvest, so those farmers are closely monitoring those tanks.

[WARNING] My opinion about a couple of things.

Old people social media (I fall into that category) is ablaze with the impending reduction of S.S. in 2033. Don't get me wrong, as I am concerned, but I am also a huge skeptic regarding anything meaningful being done. 

1st, the notion an uprising will take place if the cuts are made... ludicrous. We would be alone in our outrage, as we have known for several decades about this problem and are now taking it serious. Can we really expect our descendants to get alarmed about something we ignored for so long? NO.

2nd, the idea that erasing the cap and adding another 2% onto OASDI withholding. Not just 2% more, but raising the current rate 2%. That might well raise the necessary $400+ BILLION ANNUALLY, to keep SS whole. It would represent one of the largest tax increases in my memory, just to keep something younger generations consider a lost cause. Think about it... we are raising their taxes, so we can keep our S.S. whole.

3rd, raising the aforementioned taxes would do nothing to alleviate the national debt, fiscal deficits, interest on debt... of which is beginning to spiral out of control. 

4th, raising taxes is never popular among a certain income level, and neither is reducing spending in areas that affect another income level. 

5th, It is lunacy to expect anyone in either camp to actually propose the serious and necessary solutions, let alone get them through Congress. Anyone that actually sees the seriousness of this issue, is not even interested in being in politics.

6th, The "C(*&" is going to hit the fan, so how can I best prepare to weather the storm? If I die before that happens, then I would be okay, although I would rather not die anytime soon. AND it is gonna get here sooner... rather than later, imo.

Feel free to suggest possible solutions.

Thursday, October 15, 2026

The latest petroleum inventories (Oct-15-2026)

Inventories edged up for gasoline and jet fuel. However, distillates and crude dropped, as the total of all products decreased nearly 13.5M barrels. The SPR showed no movement from last week. 

There is still a plan to release an additional 40M barrels from the SPR, in the November-December timeframe, via an exchange program to be released at some unspecified "date" in the future. 

Additionally, the EU is releasing crude products with a front load of distillates over a 4 month period. Which sounds nice, and will likely slow the rise in diesel prices, but for a very short timeframe, imo. Additionally, the notion of "allowing" off road diesel, sans federal excise taxes, until the beginning of the year is nothing but politics for the non users of diesel, as no one in their right mind would take advantage of such an offer.


The consumption of gasoline fell on both y/y and week to week. 


For the record... the national average for diesel at the pump is 72.8% higher than this date last year. 

While I am not seeing much movement in gasoline prices, the diesel seems to be slated to go much higher. 

Here are my current projections...

That's a wrap for this week. If any questions... simply ask.


Wednesday, October 7, 2026

The latest petroleum inventories (Oct-07-2026)

Inventories edged up for gasoline, with jet fuel, distillates, and crude slipping, as the total of all products decreased nearly 7.8M barrels. The SPR decreased about 700KB. 

I still hear a plan to release an additional 40M barrels in the November-December timeframe, via an exchange program to be released at some unspecified ?date? in the future. 

Additionally, the EU is releasing crude products with a front load of distillates over a 4 month period.


The 4 week running average of gasoline consumption edged up this period.


China and Russia are still excluding distillates from export, so the EU release might not move the markets that much. 

The potential for a hurricane along the U.S. Gulf Coast does not seem to be moving the markets... and might not.

A bit of an editorial...

Nearly 25 years ago, I gave serious consideration to the notion of early retirement. Of course, how would my savings and investments stack up against a wide variety of economic conditions. 

One of my first observations was the impact of the 1973 oil embargo and the 1980 Iranian revolution, certainly had an impact. The impact was mostly felt in consumer confidence and spending habits as people cut back in anticipation of rough times. 

At this point... not seeing significant cutbacks in consumer spending, although the "confidence" surveys indicate a lot of worry.

I would watch this very carefully, as a dip in confidence and spending could portend serious problems ahead. 

In nearly all previous jolts to the economy, government spending came to the rescue. I would suggest that any future economic jolts might become very severe... due to all the previous excessive spending and the expectation of even more.

At what premium will investors require to purchase the U.S. debt? At what point will the FED need to raise interest rates to keep dollarized assets attractive to investors to government treasuries? I am already convinced that future rates are going to take place, to not only "tame" inflation, but prop up the dollar and thereby the global banking system, which is heavily indebted in dollars. 

Any dip in the economy could quickly escalate into something far greater that the "Great Recession".

Be prepared!!

Wednesday, September 30, 2026

The latest petroleum inventories (Sep-30-2026)

Inventories edged down for gasoline, jet fuel and distillates, with crude rising, as the total of all products decreased nearly 8M barrels. The SPR decreased about 700KB. Originally, 172M barrels were slated to be pulled, AND within 5 months(?). 130.6 Million barrels have been pulled and the drawdown has slowed significantly, with l00K barrels a day for last report, which is up slightly from last week. 

I have heard there is a plan to release an additional 40M barrels in the November-December timeframe, via an exchange program to be released at some unspecified ?date? in the future.

Gasoline consumption declined on both the y/y and d/d, based on the moving 4 week average.


Diesel continues to be the big story, with no relief in sight, imo. Much is made of the crack spread on diesel, but I question some of those numbers. Typically, everyone uses the 3:2:1 method to calculate the spreads and reasonably associate that number with the refinery profitability margin. 

The problem being the base unit being either the WTI or Brent benchmark, which excludes the shipping costs, insurance, etc. What appears to be excessive refinery margins, turns into profitability of insurance and shipping companies. This is particularly true for crude coming out of the Persian Gulf and destined for Asia. 

Any consideration of halting or slowing distillate exports would run into another set of problems. With most of the refined distillate for export sitting along the Gulf Coast... how to get it back into the U.S. heartland. 

There are existing pipelines that could be used, but might require displacement of some gasoline product, which would drive gasoline pump prices higher. It could balance the disparity in gasoline and diesel prices, but at what cost to the average person't pocketbook?

Then there is the issue of distillate fuel in Europe, which is the prime destination for a lot of this distillate export. Europe is already in dire straits over the natural gas inventory, unless a very, every mild winter. 

Food for thought!

Wednesday, September 23, 2026

The latest petroleum inventories (Sep-23-2026)

Inventories edged down for gasoline and distillates, with crude and jet fuel rising, as the total of all products decreased -0.3KB. The SPR decreased about 400KB. Originally, 172M barrels were slated to be pulled, AND within 5 months(?). 130.6 Million barrels have been pulled and the drawdown has slowed significantly, with less than 60K barrels a day for last report, which matches last week. 

Gasoline consumption declined on the y/y and remained in place for the 4 week running average.


I have lamented the diesel prices of the past few weeks, but that pump price may actually be nearing its apex. 

Wednesday, September 16, 2026

The latest petroleum inventories (Sep-16-2026)

Inventories moved up for gasoline and distillates, with crude and jet fuel easing, as the total of all products increased +2.2MB. The SPR decreased about 400KB. Originally, 172M barrels were slated to be pulled, AND within 5 months(?). 130.2 Million barrels have been pulled and the drawdown has slowed significantly, with less than 60K barrels a day for last report. 


Gasoline consumption contines to decline on both y/y and m/m.


Gasoline prices continue to edge up, but diesel is the big story. Nationally, diesel prices will leap past $7 and California diesel with likely surpass $9.


The current national average of diesel, is at an all time high of $5.816 and when adjusting for inflation, is nearing the inflation adjusted figure of $6.554. It will surpass that shortly and will make a run for the July 2008 $4.767 inflation adjusted figure of $7.237.

While a lot of the issue is surrounding the Strait of Hormuz, the Ukraine shelling of Russia's refineries, and Russia limiting exports of refined products... also plays a role. 

At some point, natural gas will be an issue in Europe, but not my focus. U.S. stocks of NG are in decent shape and pricing not too out of the ordinary. For those interested in Europe, here is their website.


Thursday, September 10, 2026

The latest petroleum inventories (Sep-10-2026)

Inventories moved up across the board, as the total of all products increased 5+MB. The SPR decreased about 1.2MB. Originally, 172M barrels were slated to be pulled, AND within 5 months(?). 129.8 Million barrels have been pulled and the drawdown has slowed significantly. 


Gasoline consumption contines to decline on both y/y and m/m.


Gasoline prices are edging up, but the story is still about diesel, imo. Diesel is set to blow past the near $6 mark towards the $7 mark nationally, and hold your breath California... from current near $8, to near $9 per gallon. Much of this was explained in my previous post. 

Stay tuned.

Wednesday, September 2, 2026

The latest petroleum inventories (Sep-02-2026)

A mixed bag, with crude falling, as well as gasoline, jet fuel and SPR. Distillate edged up, as well as Jet fuel. 


Gasoline consumption is edging downward on a 4 week moving average. -2.8% compared to year ago levels, and -0.5% on the week to week 4 week average.


Pump prices for gasoline are staying in a somewhat narrow band. However diesel prices could very well break through all time highs, set in June of 2022. $6+ for a national average is certainly within the realm of possibility, with California diesel possibly topping $8 in the near future. 


So some fun facts. The U.S. consumer uses about 1/3 of global gasoline consumption, while the U.S. refiners produce about 1/6 of global diesel product, after export the U.S. consumes... about 12% of global diesel products. 

U.S. refiners are operating at near record levels, to meet the demand. The global demand of diesel... is driving the price upward, at an astonishing pace. Despite refining about half as much diesel, as gasoline, the refiners are making 70% more on that diesel. 

One would think the refiners might wish to make even more, by tweaking the process to produce more diesel. While that is theoretically possible, it would also cause gasoline stocks to slip, thereby driving up gasoline pump prices, which is more politically visible. 

So while there is a bit of stability in gasoline prices, the diesel market will be allowed to escalate prices until, it becomes politically visible. However the majority of the public will focus on the pump price directly in their face and a minority will possibly virtue signal their indigation of diesel prices.

What I am saying is... diesel prices are set to rise another 82¢ a gallon from today's price, while gasoline will likely stay in their current range.

Feel free to bookmark and come back in a few weeks, to see how accurate I am, or point out my inaccuracies. 

Saturday, August 29, 2026

Another week with the crude report from EIA.GOV.

Let's get the inventory numbers out of the way...

There is some y/y decline in the 4 week average of consumption...

Pump prices are somewhat steady on the gasoline side, although edging up on the diesel side. 

The prices still haven't broken through the 2022 highs and would have a long way to go in inflation adjusted dollars. The inflation adjusted figures are even more startling for 2008.


There is an old saying that we should learn from our mistakes. But are we able to learn from our mistakes, if we constantly blame others???

Friday, August 21, 2026

Should I Start Posting Again... or Not!

It has been awhile, although I have kept abreast of a few things.

First up... is inventory status of select energy components in the USA.

The SPR status is slowly declining, with the unknown being how much spoilage is there. At current rates of withdrawal, about 50 weeks remain... IF there is no spoilage. The Cushing inventory, which is included in the Crude numbers... is low, but not critical, given historical number. 

Of course, the BIG story is pump prices of gasoline. 


I would be a bit more concerned with the Diesel prices, but hey...


Gasoline consumption is -1.7% from last year, with it being -0.4% from last week. Whatever the price, the consumer seems to be adjusting, although still complaining. 

Looking forward, and based on current market pricing...


An uptick in gasoline is in the offing, but the diesel is set to rise rather swiftly, imo.

That finishes up this episode of an old guy foolishly expressing his opinion.

Thursday, May 7, 2026

Some thought on May 7th, 2026... about energy, etc.

It's been awhile since posting, although I never really stopped tracking. 

Current U.S. inventories, compared to last week and 1 year ago.


Not terribly tight and I really don't see a significant drop off in U.S. consumer purchasing at the pump. Distillate exports reached an all time high during this reporting period. Additionally, the distillate inventory has dropped to levels not seen since 5/23/2003.

Pump prices compared to days gone by, factoring in inflation...

That $4.114 in July, 2008 is comparable to $6.176 in today's dollars. Also, the $5.016 of June, 2022 is comparable to $5.590 in today's dollars.

The market does seem to be settling down a bit, but I suspect that is more fear of getting caught over bought, due to some very clear demand destruction in Asia. Much was made if that 470M Barrels being released from various strategic petroleum reserves, but that is a drop in the bucket to the near 1B barrels that have been lost to the strait of hormuz blockade, etc.

Even if the blockade suddenly stopped tomorrow and the full complement of crude starts tomorrow... another 500M barrels will be removed from the global inventories, due to transit times of delivey. If you are keeping track... that is 1B barrels above the SPR release.

That demand destruction is taking place, is undeniable. Even with significant demand destruction of 5M barrels per day... it would take 6 months for a full recovery, imho.

What I find interesting, is the lack of discussion of the current state of natural gas supplies. Qatar suffered a severe setback in its LNG liquefaction facilities. It will take some time to resolve that situation and while there are new Liquefaction facilities coming on line later this year... the current state of the European Union's Natural Gas storage if behind last year, with draws still above last year. 

Purchases of Natural Gas for storage is woefully behind last year. Perhaps they see a milder winter coming up over the next 12 months. I guess what I am hinting at... Natural Gas prices in Europe are set to dramatically escalate in the coming months, OR... they may decide to swallow some pride and get some of that pipeline natural gas from somewhere.


Wednesday, February 12, 2025

A Few Reports and some opinions... of course!

The CPI came out today and now that Trump is in office, it has suddenly turned terrible. Nevermind, it is for January, so remarkable for just 11 days in office. /s

The media's memory is a bit wacky, with claims that it has suddenly shifted upward, even though the lowest annual rate since February 2021 was this past September.

A trip down memory lane...

The real earnings report has been ignored and for good reason... weekly wages, when adjusted for inflation have now fallen back to June, 2024 levels. That's seven months, since weekly wages adjusted for inflation have been this low.
Note: The BLS reports both CPI and Real Earnings.

As for the energy report from the EIA, not much in extreme changes. Pump prices will likely rise, but should be noted... still below year ago levels. Of course, the rise will become political, as everything else.


Tariffs... A lot of talk about the damaging effects of tariffs, but the whole matter of FTZ status of dozens of companies have been ignored. A FTZ or "Foreign Trade Zone" status, means a company pays no tariffs, until the end product is sold to the public. There are many large and small companies with FTZs, which include energy companies (refineries, etc.) and automobile companies with their component assemblies. 

Once you understand the magnitude of FTZs, then you should consider that tariffs have long been in existence. 

Another serious argument put forth by many... is the Smoot Hawley act devastated the U.S. Economy during the depression, or at least made it worse. Not sure correlation was causation for this period. It does give the trade aficionados a talking point.

Yes, tariffs will cause inflation. However, off shoring of goods was a primary reason for the erosion of the middle class in the U.S. We basically beat inflation, by utilizing cheap foreign labor. We cannot hope to restore the middle class, without reshoring. 

It really is that simple. 

Friday, December 27, 2024

This Week in Petroleum Summary December 27th, 2024 per EIA.GOV

This week's full report.  

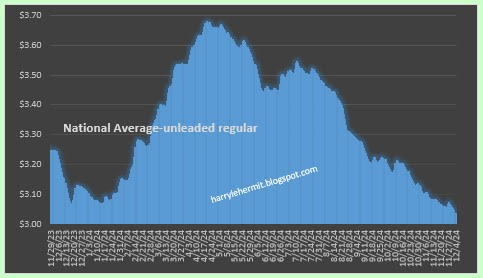
Gasoline pump prices fell -1.6¢ for the week, but continues below year ago levels, by -8.8¢, or -2.88%. Days supply fell to 25.2. For perspective... last year was 25.7 days. 


Inventories were mixed , with crude down -4.2M barrels; Distillates down -1.7M barrels; Gasoline stocks rose +1.6M barrels. Total Petroleum + products +SPR slipped -12.4M barrels, with the SPR rising +260K barrels.

The total products is still +16.2M barrels ahead of year ago levels. 

For those interested, the exports of Crude, Petroleum Products, Including Gasoline has far outweighed the imports, by this much, since March, 2022.


The current crack spread fell from last week's $16.89, to $16.68. Gasoline rose to $7.74, from last week's $7.68. Distillates fell to $8.94, compared to last week's $9.22. Per barrel of diesel is $29.60; Per barrel of gasoline is $17.02. Generally speaking... above $25 indicates rises. 


The data sets for gasoline, continue to diverge with price movement in the coming days, within a narrow band, imo. -1.7¢ ~ +1.9¢. There does seem to be some upward movement in diesel.

With the profitability of diesel increasing, the potential for added refining could increase gasoline supplies, which has been shown of late. So it is possible that gasoline will continue somewhat lower, but diesel appears to be headed up. 

Time will tell.

I will continue to track the Energy Reports for personal reasons, I will discontinue publications of going forward]

Wednesday, December 18, 2024

This Week in Petroleum Summary December 18th, 2024 per EIA.GOV

This week's full report.  

Gasoline pump prices rose +1.4¢ for the week, but continues below year ago levels, by -3.2¢, or -1.2%. Days supply fell to 25.4. For perspective... last year was 26.5 days. 


Inventories were mixed , with crude down -934K barrels; Distillates down -3.2M barrels; Gasoline stocks rose +2.3M barrels. Total Petroleum + products +SPR slipped -2.7M barrels, with the SPR rising +519K barrels.

The total products is still +11.6M barrels ahead of year ago levels. 

For those interested, the exports of Crude, Petroleum Products, Including Gasoline has far outweighed the imports, by this much, since March, 2022.


The current crack spread fell from last week's $17.11, to $16.89. Gasoline fell to $7.67, from last week's $8.38. Distillates rose to $9.22, compared to last week's $8.72. Per barrel of diesel is $30.53; Per barrel of gasoline is $16.86. Generally speaking... above $25 indicates rises. 


The data sets for gasoline, continue to diverge with price movement in the coming days, within a narrow band, imo. -.02¢ ~ +4.2¢. There does seem to be some upward movement in diesel.

With the profitability of diesel increasing, the potential for added refining could increase gasoline supplies, which has been shown of late. So it is possible that gasoline will continue somewhat lower, but diesel appears to be headed up. 

Time will tell.

Wednesday, December 11, 2024

This Week in Petroleum Summary December 11th, 2024 per EIA.GOV

This week's full report.  

Gasoline pump prices slid -1.3¢ for the week, but continues below year ago levels, by -13.3¢, or -4.2%. Days supply rose to 25.5. For perspective... last year was 26.3 days. 


Inventories were mixed , with crude down -1.4M barrels; Distillates up +3.2M barrels; Gasoline stocks rose +5.1M barrels. Total Petroleum + products +SPR slipped -195K barrels, with the SPR rising +724K barrels.

The total products is still +17.7M barrels ahead of year ago levels.

For those interested, the exports of Crude, Petroleum Products, Including Gasoline has far outweighed the imports, by this much, since March, 2022.

The current crack spread fell from last week's $17.41, to $17.11. Gasoline fell to $8.38, from last week's $8.73. Distillates slid to $8.72, compared to last week's $8.68.

The data sets for gasoline, continue to diverge with price movement in the coming days, within a narrow band, imo. -3.1¢ ~ +4.4¢. There does seem to be some upward movement in diesel.

We may be nearing the end of downward pressures on gasoline. Just have to wait and see.

Wednesday, December 4, 2024

This Week in Petroleum Summary December 4th, 2024 per EIA.GOV

This week's full report.  

Gasoline pump prices slid -0.4¢ for the week, but continues below year ago levels, by -20.9¢, or -6.4%. Days supply rose to 24.5. For perspective... last year was 26.2 days. 


Inventories were mixed , with crude down -5.1M barrels; Distillates up +3.4M barrels; Gasoline stocks rose +2.4M barrels. Total Petroleum + products +SPR slipped -3.3M barrels, with the SPR rising +1.4M barrels.

The total products is still +7.9M barrels ahead of year ago levels.

For those interested, the exports of Crude, Petroleum Products, Including Gasoline has far outweighed the imports, by this much, since March, 2022.

The current crack spread fell from last week's $17.96, to $17.41. Gasoline fell to $8.73, from last week's $8.76. Distillates slid to $8.68, compared to last week's $9.21.

The data sets continue to diverge with price movement in the coming days, within a narrow band, imo. -2.4¢ ~ +3.6¢. 

Still, just as the past few weeks... nothing dramatic in the way of prices surging, or at least for now and should continue until the Christmas holiday, imo.

The latest petroleum inventories (Oct-28-2026), AND more of my grumbling!

Off to the races... Gasoline inventories rose, with all else falling.  The consumption of gasoline continues to decline. The pump price for ...